The short answer
- —Florida new construction insurance often costs significantly less than insuring an older home, because modern homes are built to current wind code and carry mitigation features insurers reward.
- —Roof age and shape, impact-rated windows, reinforced roof-to-wall connections, and elevation all factor into wind-mitigation credits that lower premiums.
- —A home built to Florida's current code typically qualifies for the strongest mitigation credits available — savings that compound every year you own it.
- —Insurance pricing varies widely by insurer, location, elevation, and coverage; the comparisons here are illustrative, not quotes.
- —Always confirm a specific home's projected premium with a licensed Florida insurance agent before relying on any savings estimate.
Yes — Florida new construction insurance typically costs less than insuring an older home. A new build meets the current Florida Building Code from day one, so its new roof, impact-rated openings, and strapped roof-to-wall connections qualify for wind-mitigation credits that lower the premium once a qualified inspector verifies them on Florida’s uniform mitigation form.
Quick Answers
Does a new build automatically get the wind-mitigation credits? The qualifying features are built in, but the credits are applied once a qualified inspector verifies the home on Florida’s uniform mitigation verification form and your insurer processes it.
Do I still need flood insurance on a new construction home? Often, yes. Flood is a separate policy from homeowners and wind coverage, and whether you need it depends on the home’s flood zone and elevation — confirm with your insurer and your lender.
When should I get the actual quote? Before you waive contingencies. Only a licensed Florida insurance agent can turn the structural advantage into a confirmed premium for your specific home.
Is Florida New Construction Insurance Cheaper Than Insuring an Older Home?
In most cases, yes — and the reason is structural, not promotional. Florida new construction insurance covers homes built to the current Florida Building Code, and that distinction is exactly what moves the premium. Because a new build’s wind-resistance features are part of the construction standard rather than retrofits added later, insurers can apply the strongest mitigation credits available. Older homes can close some of the gap with renovations, but a newly built home starts with the advantage already in place — and it carries forward for as long as you own the home.
What Specific Features Lower Insurance Costs on New Builds?
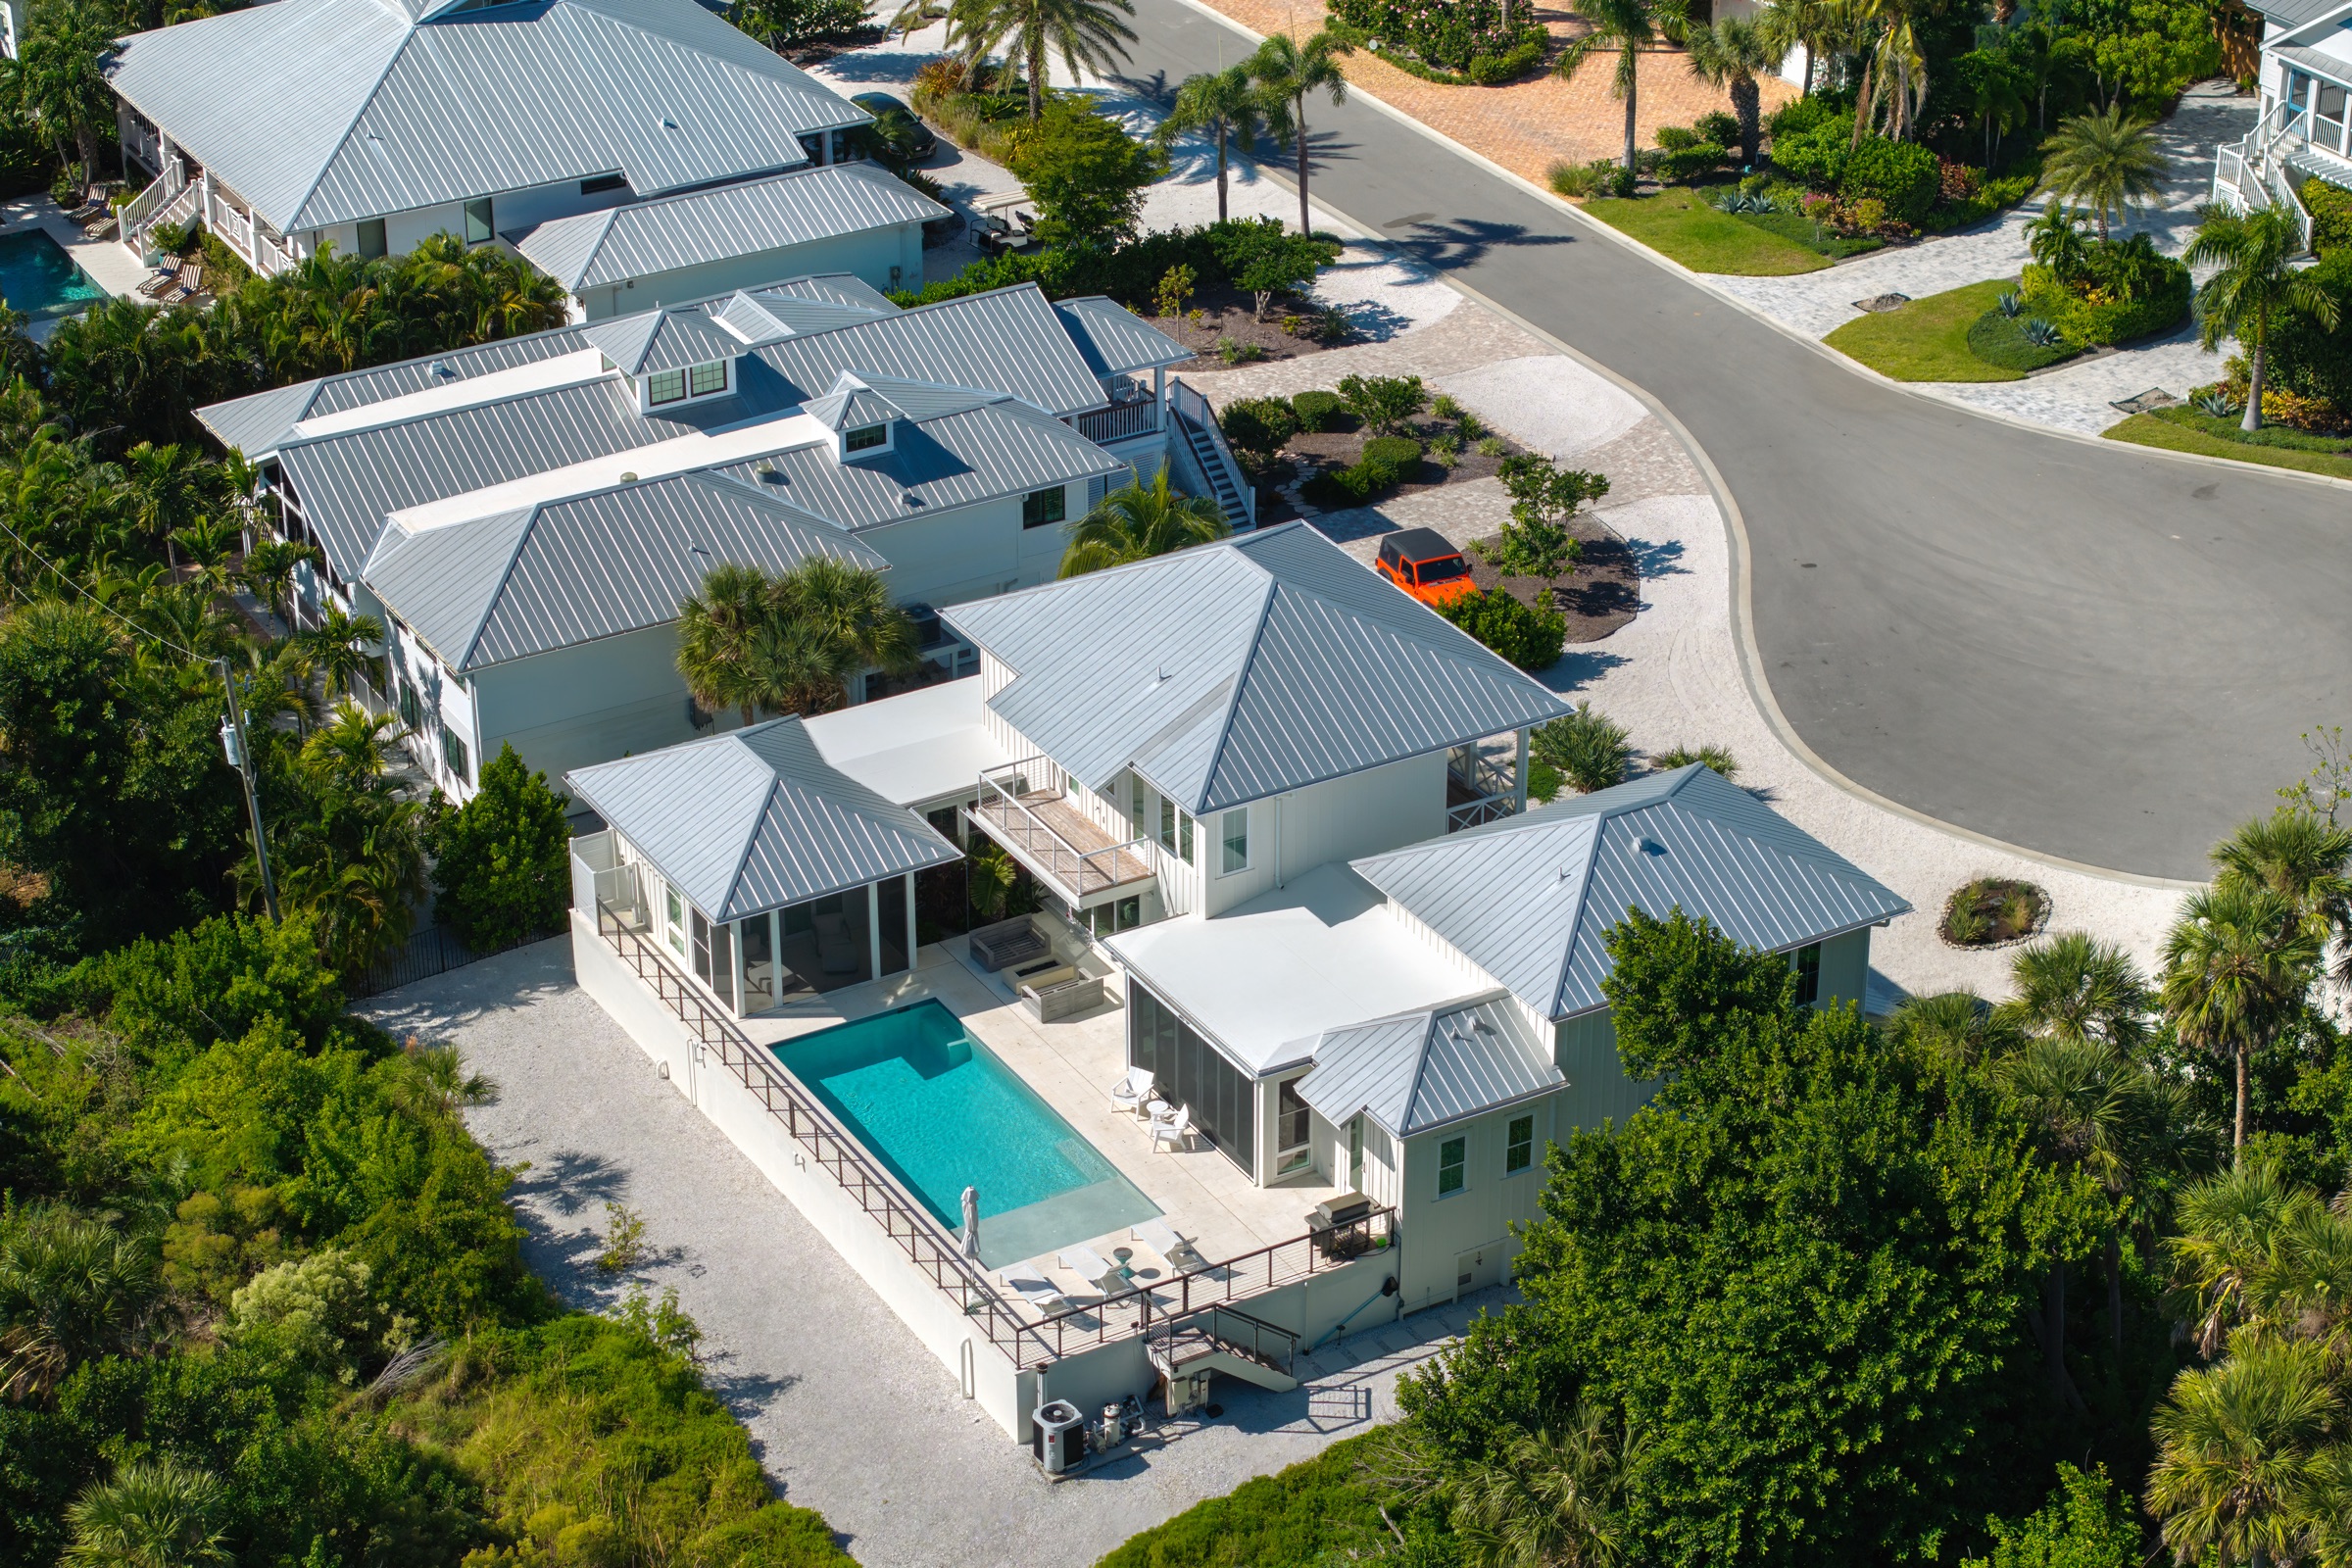
Insurers price wind risk feature by feature, and new construction arrives with the top-rated version of each one already in place. That is what qualifies these homes for the strongest wind-mitigation credits on features like hip roofs, roof-to-wall straps, and secondary water barriers.
The features that matter most:
- Roof shape. Hip roofs (sloped on all sides) resist uplift better than gable roofs and earn stronger credits.
- Roof-deck attachment. How the roof sheathing is fastened to the trusses — modern nailing patterns outperform older standards.
- Roof-to-wall connection. Hurricane clips or straps that tie the roof to the walls, versus older toe-nailed connections.
- Secondary water barrier. A sealed roof deck that limits water intrusion if the covering is lost.
- Impact-rated openings. Windows and doors rated to withstand wind-borne debris, which can also reduce or eliminate the need for shutters.
Each of these is a line item on the mitigation form, and a new home usually checks every one by default. The result is that hurricane code savings aren’t a bonus you chase — on new construction, they’re the baseline.
How Much Does Florida New Construction Insurance Cost?
Buyers want a number, so here is an honest framing. The table below is illustrative, not a quote — actual premiums depend on the insurer, location, elevation, coverage limits, and the specific home. Always confirm with a licensed Florida insurance agent.
| Home profile | Roof / mitigation | Relative premium (illustrative) |
|---|---|---|
| New construction, current code | New roof, full mitigation credits | Lowest |
| Renovated older home | Newer roof, partial mitigation | Moderate |
| Older home, updated openings | Aging roof, some credits | Elevated |
| Older home, no mitigation | Old roof, no documented features | Highest |
The pattern is consistent across the market: the further a home sits from current code and a new roof, the more it costs to insure. The exact spread varies, but the direction never does. An older, unmitigated home of similar value can cost far more to insure year after year — which is why insurance belongs in any serious total-cost comparison, as we cover in the broader Gulf-coast new-construction investment case.
What Is a Wind Mitigation Inspection and Who Can Sign the Form?
It’s worth understanding the paperwork, because that’s where the savings become official. In Florida, mitigation credits are not applied automatically; they require verified documentation. Section 627.711, Florida Statutes, requires insurers to notify every personal-lines residential policyholder of the availability and range of hurricane-mitigation discounts at issuance and at each renewal, and directs the Financial Services Commission to prescribe a uniform mitigation verification inspection form that all insurers must use when a policyholder submits it for wind-discount purposes. The same statute lists who may complete and sign the form: a licensed home inspector with approved hurricane-mitigation training, a certified building code inspector, a licensed general/building/residential contractor, a licensed professional engineer, or a licensed architect. The inspector verifies and records each qualifying feature: roof shape, roof-deck attachment, roof-to-wall connections, secondary water barrier, and opening protection.
For an older home, this inspection is a moment of truth — it can reveal that previously assumed features don’t actually qualify, or that an aging roof undercuts everything else. For new construction, it’s typically a formality that confirms what the build already includes: a home constructed to current code generally qualifies for the strongest available credits, because those features are baked into the construction standard rather than added later. That predictability is part of the value. You aren’t relying on an inspector to uncover qualifying features hidden behind drywall; you know they’re there by design.
Should Insurance Change Which Florida Home You Buy?
Yes — because careful buyers don’t evaluate a home on price alone. They model the carrying cost over years of ownership, and insurance is one of its largest and most volatile lines. Two homes can list at similar prices and diverge sharply once you add insurance, with the older home costing more to insure every year. Over a typical hold period, that gap compounds into a meaningful number — one that directly affects net yield for an investor and monthly affordability for a family.
This is why a code-built home’s lower premium is more than a one-time perk. It’s a recurring structural advantage that improves cash flow, reduces the risk of a sudden non-renewal forcing you into the surplus-lines market, and makes the home easier to finance and eventually resell — because the next buyer inherits the same favorable insurance position. When you compare properties, ask for the insurance picture early; it can change which home is actually the better buy, sometimes reversing what the sticker prices suggest.
Do I Still Need Flood Insurance on a New Build in Florida?
Yes, possibly — and honesty matters here, so two caveats. First, wind mitigation and flood insurance are separate. Standard homeowners and wind policies generally don’t cover flood — that requires a separate policy, often through the NFIP or a private insurer, and whether you need it depends on the home’s flood zone and elevation. The good news is that a newly elevated, code-built home may carry lower flood premiums; the rule is to confirm the flood zone and requirements with a licensed insurer and your lender.
Second, the Florida market itself moves. Insurer appetite, reinsurance costs, and statewide pricing shift over time, and even a new home’s premium isn’t fixed forever. New construction gives you the strongest structural position available — but it’s a position within a market, not immunity from it. Build your purchase math on confirmed quotes, not assumptions.
Is a New Build Worth It for an Investor Once You Price the Insurance?
For an investor, Florida new construction insurance is a recurring advantage that compounds. Lower premiums every year improve net yield, reduce the risk of a non-renewal surprise, and make the home easier to finance, insure, and eventually resell. Stack that on top of modern construction, lower maintenance, and the resilience that protects the asset itself, and insurance stops being an afterthought — it becomes part of the return.
That logic applies wherever you’re buying on the Gulf coast — the canal homes of Punta Gorda Isles, the new builds of Cape Haze, and beyond. If you’re early in the process, our buying new construction in Florida guide and the questions buyers ask page cover what to verify before you commit.
One last piece of practical advice: get the insurance quote before you waive contingencies, not after. Florida’s market can surprise even experienced buyers, and the only way to turn a structural advantage into a confirmed number is to put the specific home in front of a licensed insurer early in the transaction. A new build gives you the strongest possible starting position — current code, a new roof, full mitigation credits — but the actual premium still depends on the carrier, the flood zone, the elevation, and your coverage choices.
Treat the quote as part of your diligence, the same way you’d treat an inspection or a survey. Buyers who do this avoid unpleasant surprises — and often find the insurance math makes the case for new construction even more decisively than the listing price did.
Where OceanFL fits: OceanFL is buyer-side. Sabatino Campilii represents you — and part of representing a buyer well on the Gulf coast is helping you see the full cost picture, insurance included, before you fall in love with a home. We don’t quote premiums; a licensed insurer does that. What we do is steer you toward homes whose construction and code position give you the strongest position when those quotes come in, so the numbers work in your favor for years.
Ecolosophy: Stage your new investment to appeal to every buyer with our Unscented Oasis kit — small-batch, made with care, and designed to create a pristine, welcoming environment for showings, walkthroughs, and closing day alike.
Sabatino can answer it in five minutes — no pressure, no listing-agent spin.
Sources cited
- Section 627.711, Florida Statutes — Notice of premium discounts for hurricane loss mitigation; uniform mitigation verification inspection form — The statute that requires insurers to disclose wind-mitigation discounts and to accept the uniform mitigation verification form.
- Florida Office of Insurance Regulation — State regulator; publishes approved discount ranges by insurer and the prescribed mitigation forms.
- Florida Building Commission — Florida Building Code — The code new construction is built to, including wind-borne debris and roof requirements.
- FEMA — Flood Insurance (National Flood Insurance Program) — Flood is a separate policy from homeowners and wind coverage.
- Citizens Property Insurance Corporation — Florida's residual-market insurer, referenced in s. 627.711(9) on mitigation form verification.
Realtor®, LoKation® Real Estate
25-year builder, developer, and licensed Realtor® representing buyers and sellers across the Southwest Florida Gulf-coast pockets. Reviewed and published March 30, 2026. Updated September 13, 2026.
Have Sabatino represent you — before you call any listing agent.