Golf Communities of Southwest Florida: Buyer’s Guide
Buying into a golf community in Southwest Florida is two transactions wearing one price tag. You are buying real estate, and you are buying a membership structure — and the second one frequently has more effect on your monthly cost and your resale pool than the first.
Buyers coming from other parts of the country often assume “golf community” describes a single thing. It does not. In this region the term covers arrangements that range from a mandatory equity purchase in a member-owned club to a public daily-fee course with houses along it and no obligation at all. Getting the structure right is the whole exercise.
How Golf Communities Are Structured
Start by separating three distinct legal layers that often coexist on the same property.
The homeowners association. This governs the residential property — architectural standards, common area maintenance, and the rules you live under. Every owner in the community typically belongs.
The club. This governs golf and often other amenities. Depending on the community, club membership may be mandatory for every homeowner, optional, waitlisted, or entirely separate from residency.
A community development district, in some communities. A CDD is a special-purpose local government created to finance and maintain infrastructure, and its assessments appear on the annual property tax bill rather than as an HOA invoice. This is a meaningful cost item that buyers routinely overlook when comparing communities. Our overview of HOA and CDD structures in Southwest Florida explains how they differ and where each shows up.
These layers can be governed by different documents, different boards, and different fee schedules. Ask for all of them.
Bundled, Equity and Pay-Per-Play Models
Bundled golf. Golf membership is attached to the home. Buy the property, you are a member; the golf dues are part of your mandatory community fees whether you play three hundred rounds a year or none. Bundled communities are common in Southwest Florida and they are typically the lower-cost entry into regular golf, because the cost is spread across every household.
The upside is straightforward: unlimited or heavily discounted play at a predictable cost, and no initiation to negotiate. The downsides are equally straightforward: you pay whether you play or not, tee time demand can be high because every household is a member, and your buyer pool at resale is limited to people willing to accept the same obligation.
Equity membership. Members collectively own the club. Joining requires purchasing an equity interest, sometimes with a refundable component on resignation, subject to the club’s own rules and often a waiting list of resigned members ahead of you. Equity clubs generally offer more control, more selective membership, and lower course congestion. They also involve larger up-front capital, annual dues, minimum spending requirements at the club, and exposure to capital assessments when the club undertakes major projects.
Non-equity or membership-for-purchase. The club is owned by a developer or an operator. Members buy a membership that grants access but not ownership. Terms vary widely, and refundability provisions deserve careful reading.
Optional and pay-per-play. Some communities sit along a semi-private or public course with no membership obligation whatsoever. You pay green fees when you play. For a buyer who golfs occasionally, this is often the rational structure and it is systematically underrated.
There is no best model. There is only the model that matches your play frequency, which we will get to.
Course Frontage: Views vs Stray Balls
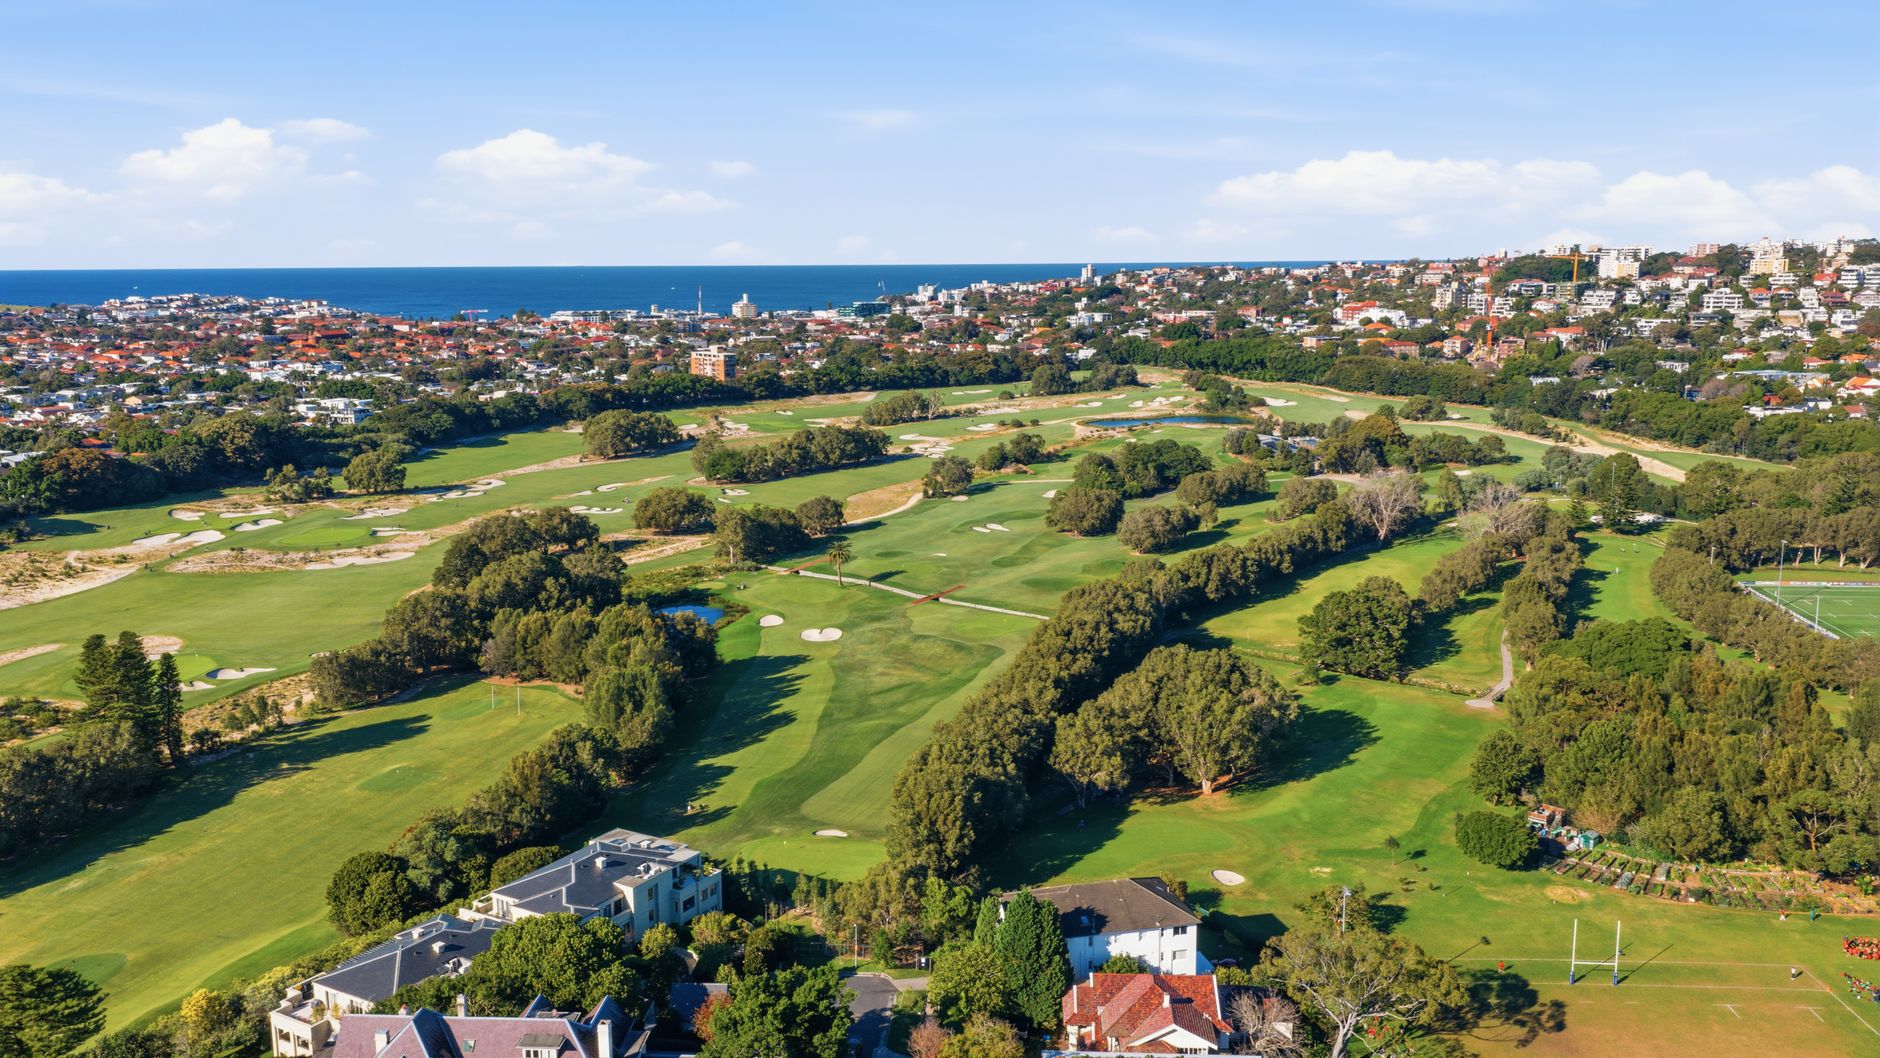
A lot on the course is priced above an interior lot in essentially every community here, and the premium is generally justified by the view — long green sightlines, mature landscaping, and no rear neighbor.
The considerations before you pay for it:
Ball strikes are real, and location-dependent. A lot along the right side of a fairway where most amateur players slice will take meaningfully more traffic than one behind a green or along a hole’s less-used side. Ask the community about ball strike history for the specific address. Longtime residents will tell you honestly.
Which direction does the hole run? A lot facing down a fairway toward a tee gives you the long view most people are paying for. A lot tucked beside a cart path gives you cart traffic.
Maintenance schedules. Courses are mowed and maintained early. If you are a light sleeper, the sound of maintenance equipment at dawn along your lot line is a real quality-of-life factor.
Irrigation and chemical application. Understand where course irrigation reaches and what the club’s practices are near residential boundaries.
Play traffic and privacy. A house eight feet from a cart path has a different daily experience than one set back forty feet behind a berm.
Netting and screening. If existing homes on the hole have netting installed, that tells you something.
Visit the lot on a busy morning during season, not on a quiet weekday in August. The character of the location is entirely different.
Amenities Beyond the Course
For most households, the golf course is not the amenity used most often. Look carefully at the rest.
Racquet sports have expanded significantly in these communities — tennis, and increasingly pickleball, which has changed the amenity mix in a lot of Southwest Florida clubs. Fitness centers, resort and lap pools, dining rooms and casual grills, marina or boat storage in waterfront communities, and social programming all belong in the evaluation.
Ask which amenities are included in your membership tier and which carry separate fees. In multi-tier clubs, a “social” or “sports” membership may include everything except golf, at a substantially lower cost — and for a household where one spouse plays and the other does not, tier structure is worth studying closely.
If boating matters alongside golf, understand how the community handles slips and whether they convey, are assigned, or are leased. Our post on buying a home with a boat slip or marina rights covers the arrangements you will encounter.
Fees, Assessments and Governing Documents
Request and actually read the following before your inspection contingency expires:
- The HOA declaration, articles, and bylaws, plus current rules and regulations.
- The club membership documents, including the membership plan, dues schedule, minimum spending requirements, transfer rules, and any refundability terms.
- The current budget and reserve study for both the HOA and, if available, the club.
- Minutes from recent board meetings. This is where planned capital projects appear before they become assessments.
- Any pending or recent special assessments, and the history of them.
- The estoppel or disclosure package provided in the transaction.
- CDD assessment information, if applicable, including the remaining term of any bond debt.
Two specific questions to ask directly. First: is club membership mandatory or optional for this address? It can vary within a single community. Second: what capital projects are being contemplated? Clubhouse renovations, course rebuilds, and irrigation replacements are large, cyclical, and paid for by members.
Also ask about the club’s financial condition and membership levels. A club losing members shifts fixed costs onto the remaining ones.
Touring a Club Before You Buy
Do not evaluate a club from a brochure or a single visit.
Play the course if you can arrange it, and pay attention to conditioning rather than layout — layout is a matter of taste, conditioning is a matter of budget and management. Eat in the dining room on a normal evening. Use the fitness center. Sit at the grill and talk to members; people are candid about their clubs.
Ask about tee time availability in the specific way that matters to you: how far in advance do members book, and can a member reliably get a weekend morning time in February? In a bundled community with a single course and full membership, that question has a real answer and you want it.
Ask about the waitlist, if there is one, and how long it currently runs. Ask about guest policies if you expect visitors. Ask about seasonal restrictions, since many clubs operate differently outside the winter season.
Matching a Club to Your Play Frequency
The simplest honest framework:
You play two or three times a week, most of the year. Bundled golf is usually the best value available, and equity membership is worth it if you want conditioning, congestion levels, and control that bundled clubs generally cannot match.
You play a few times a month during season only. Look hard at optional-membership communities or a home near a semi-private course. Paying full bundled dues year-round for seasonal play is a common and expensive mismatch.
You play a handful of times a year, or your household is split. Pay-per-play, or a social membership tier in a community with strong non-golf amenities, will almost always serve you better than mandatory golf.
You want the setting more than the game. Plenty of buyers want the view, the space, and the manicured environment without any interest in playing. Optional-membership communities exist precisely for you — and buying into a mandatory bundled community for the aesthetics means paying golf dues for a landscape.
One last resale consideration: a mandatory membership narrows your future buyer pool to people who accept that obligation. That is not a reason to avoid these communities, but it is a reason to be honest about which structure you are signing into.
If you would like help comparing specific Southwest Florida golf communities — including how their fee structures and documents actually read side by side — contact Sabatino Campilii. Reviewing the membership plan alongside the HOA budget before you write an offer is the step that prevents the surprises.
Sabatino can answer it in five minutes — no pressure, no listing-agent spin.
Realtor®, License SL3363040
25-year builder, developer, and licensed Realtor® representing buyers and sellers across the Southwest Florida Gulf-coast pockets. Reviewed and published July 3, 2026.
Have Sabatino represent you — before you call any listing agent.