The short answer
- —A wind mitigation inspection documents features that help your home withstand hurricane-force winds.
- —Cocoa Beach homeowners often see insurance savings after completing the inspection.
- —The inspection covers roof shape, roof-to-wall attachments, and opening protection like shutters or impact windows.
- —Results are typically valid for several years, so timing the inspection matters.
- —Newer construction and updated roofs tend to score better on wind mitigation credits.
What is wind mitigation in Cocoa Beach?
Wind mitigation in Cocoa Beach is a home inspection that documents features protecting a property from hurricane-force winds. Inspectors look at the roof, walls, and openings to determine how well a home is built to resist wind damage. The results are then submitted to insurance carriers, who may offer discounts based on what’s found.
For homeowners along the Space Coast, this inspection isn’t just paperwork. Cocoa Beach sits directly on the Atlantic, which means every property here faces real hurricane exposure. Insurance companies know this, and they price policies accordingly. A wind mitigation report gives them a clearer picture of your specific home’s risk, rather than a blanket assumption based on zip code alone.
Why does wind mitigation matter for Cocoa Beach homeowners?
It matters because it can directly affect your insurance premium. Coastal Florida homes carry some of the highest windstorm insurance costs in the state, and Cocoa Beach is no exception given its beachfront location.
When an inspection shows your home has features like a hip roof, reinforced roof-to-wall connections, or impact-rated windows, insurers often apply credits that lower your annual premium. Without documentation, carriers may assume the worst-case scenario for an older or unknown-condition home. The inspection replaces assumption with evidence, which works in your favor when your home has been updated or built to more recent code standards.
What does a wind mitigation inspection actually check?
A wind mitigation inspection checks several specific building features, not the whole house. Inspectors typically evaluate:
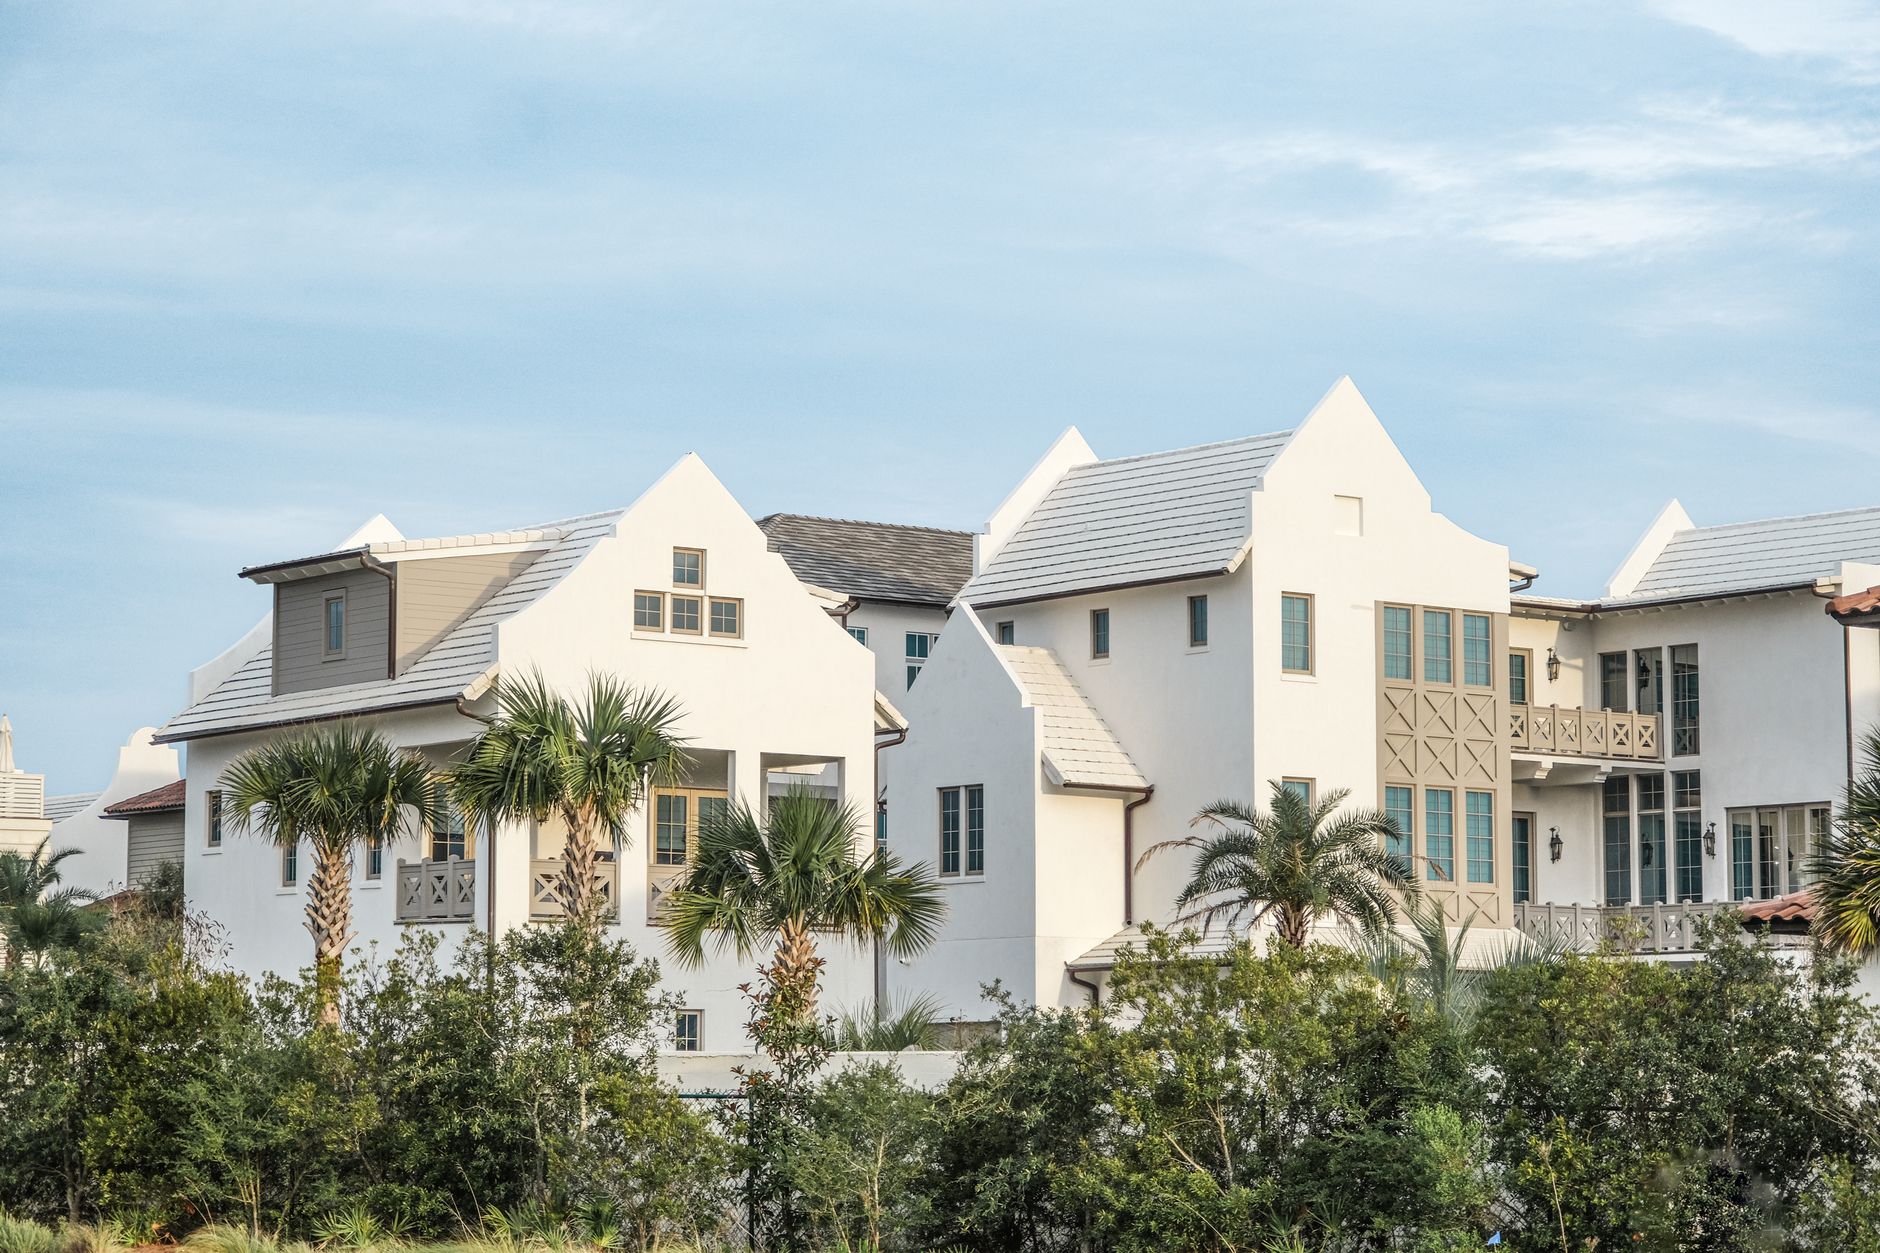
- Roof shape — hip roofs generally perform better in high winds than gable roofs
- Roof deck attachment — how the roof sheathing is fastened to the trusses
- Roof-to-wall connection — whether straps, clips, or older nail-only methods secure the roof to the walls
- Secondary water resistance — an extra barrier under the roof covering
- Opening protection — shutters, impact windows, or reinforced garage doors
Each of these is scored individually, and the combination determines the overall credit potential. A home with hurricane straps and impact windows will score very differently than one with older, unreinforced construction, even if both are in the same neighborhood.
How is wind mitigation different from a home inspection?
A standard home inspection looks broadly at a property’s condition — plumbing, electrical, structural issues, and general wear. A wind mitigation inspection is narrower and specifically focused on hurricane-resistant construction details.
You can have a home in excellent overall condition that still scores poorly on wind mitigation if it lacks specific features like roof straps or impact-rated openings. Conversely, an older home in need of cosmetic work might still score well if key structural upgrades were made over the years. For a closer look at how these inspections work in coastal settings generally, see our wind mitigation inspection guide for coastal Florida homes.
When should Cocoa Beach homeowners get a wind mitigation inspection?
The best time is before renewing your insurance policy or shortly after buying a home. Many homeowners schedule it during a purchase transaction so the results are ready before the first policy quote comes in.
Existing homeowners in Cocoa Beach who haven’t had an inspection in several years may also want to revisit it, especially if they’ve made roof or window upgrades since the last one. An outdated report won’t reflect newer improvements, which means you could be missing out on credits your home now qualifies for.
Does a wind mitigation inspection expire?
Yes, most wind mitigation forms are considered valid for a set number of years by insurance carriers, though the exact timeframe can vary by policy and insurer. If your roof has been replaced or you’ve added storm shutters or impact windows since your last inspection, it’s worth getting a new one done to capture those changes.
Homeowners who bought their Cocoa Beach property with an inspection already on file should check the date. An expired or outdated report might not reflect the home’s current condition, especially after any renovations.
Who can help Cocoa Beach buyers and owners understand wind mitigation?
Sabatino Campilii, Realtor® with LoKation® Real Estate, works with Cocoa Beach buyers and homeowners who have questions about how wind mitigation factors into a purchase or ownership decision. While the inspection itself is handled by a licensed inspector, understanding how it fits into your overall home strategy — from purchase timing to long-term ownership costs — is where local real estate guidance helps.
If you’re buying in Cocoa Beach or want to understand how your current home’s construction features might affect your insurance outlook, reach out to Sabatino directly. Contact Sabatino or call 844-623-2630 to talk through your specific situation.
Sabatino can answer it in five minutes — no pressure, no listing-agent spin.
Realtor®, License SL3363040
25-year builder, developer, and licensed Realtor® representing buyers and sellers across the Southwest Florida Gulf-coast pockets. Reviewed and published August 27, 2026.
Frequently asked
How long does a wind mitigation inspection take? +
Most wind mitigation inspections take a relatively short visit, since the inspector is focused on specific exterior and attic features rather than a full home walkthrough. Scheduling and report turnaround time can vary by inspector availability.
Do I need a wind mitigation inspection if I already have hurricane insurance? +
Having a policy doesn't mean you've captured all available credits. Without a current wind mitigation report, your insurer may not know about hurricane-resistant features your home has, which means you could be paying more than necessary.
Can I do a wind mitigation inspection myself? +
No, wind mitigation inspections in Florida must be completed by a qualified, licensed inspector so the report is accepted by insurance carriers. A self-assessment won't count toward any discount.
Does the age of my Cocoa Beach home affect wind mitigation results? +
Age can play a role since building codes have changed over time, but it isn't the only factor. Updates like a new roof, added straps, or impact windows can significantly improve results regardless of a home's original construction date.
Will wind mitigation credits apply to flood insurance too? +
No, wind mitigation credits apply specifically to windstorm and homeowners insurance components, not flood insurance, which is a separate policy with its own rating factors.
Should I get a wind mitigation inspection before listing my Cocoa Beach home for sale? +
Having a current report can be helpful for buyers evaluating future insurance costs, since it gives them concrete information rather than guesswork about the home's wind-resistant features.
Have Sabatino represent you — before you call any listing agent.