Buying a Fixer-Upper on the Gulf Coast
The appeal is obvious. A dated house on a good lot, in a location that would otherwise be out of reach, with the idea that a renovation converts one into the other. On the Southwest Florida coast, where lot quality — water frontage, depth at the dock, bridge-free access — is the scarce thing and the house is comparatively replaceable, that logic is sound.
It is also the transaction type where buyers most frequently discover, after closing, that the project they priced is not the project they bought. The difference between the two is almost always regulatory rather than cosmetic. Here is what to establish before you commit.
When a Coastal Fixer Makes Sense
A coastal fixer-upper is a strong idea under a specific set of conditions:
- The lot is the asset. You are buying water depth, orientation, a wide canal, a point lot, or bridge-free Gulf access — something that cannot be created. Our guide to understanding water depth at your dock covers how to verify the part you actually cannot change.
- The structure is sound and the deficiencies are finish-level or systems-level. Kitchens, baths, flooring, and HVAC are predictable work.
- You are not on a deadline. Coastal contractor availability fluctuates, and permitting adds weeks.
- You have reserves beyond the renovation budget. Not a contingency percentage — actual reserves.
It is a weak idea when the appeal is purely price, when the structural condition is unknown, or when the plan depends on being able to expand the footprint. Expansion on a coastal lot is a permitting question first and a construction question second.
Pulling and Reading Permit History
Do this during the inspection period, on every candidate, before you spend money on anything else. It is public information and it is the highest-value hour of diligence available to you.
Each county and municipality maintains permit records. In Charlotte, Lee, and Sarasota counties, building department records are searchable by address or parcel, and the county property appraiser will give you the parcel data, recorded square footage, and year built to cross-reference against them.
What you are looking for:
Unpermitted work. Compare what you saw at the showing against what the permit record shows. Enclosed lanais that became living space, added bathrooms, converted garages, docks, seawalls, pool cages, and re-roofs are the usual suspects. Unpermitted work becomes the new owner’s responsibility, and a jurisdiction can require it be permitted retroactively, brought to current code, or removed.
Open permits. A permit that was pulled and never closed out with a final inspection is a live item on the property. Open permits routinely stall closings when they surface late.
The re-roof record. Roof age drives insurability on this coast more than almost any other single factor. The permit record gives you an actual date rather than a seller’s recollection.
Seawall and dock permits. Marine construction requires permitting, sometimes at multiple levels. A dock with no permit history is a real risk item.
Elevation and flood documentation. Ask whether an elevation certificate exists for the structure, and check the current effective FEMA flood map for the parcel.
Structural Scope vs Cosmetic Scope
The most useful thing you can do mentally is force every line item into one of two buckets and refuse to blur them.
Cosmetic scope is anything that does not change structure, envelope, or code compliance: paint, flooring, cabinetry, countertops, fixtures, interior doors, landscaping. It is predictable, competitively bid, and rarely triggers surprises.
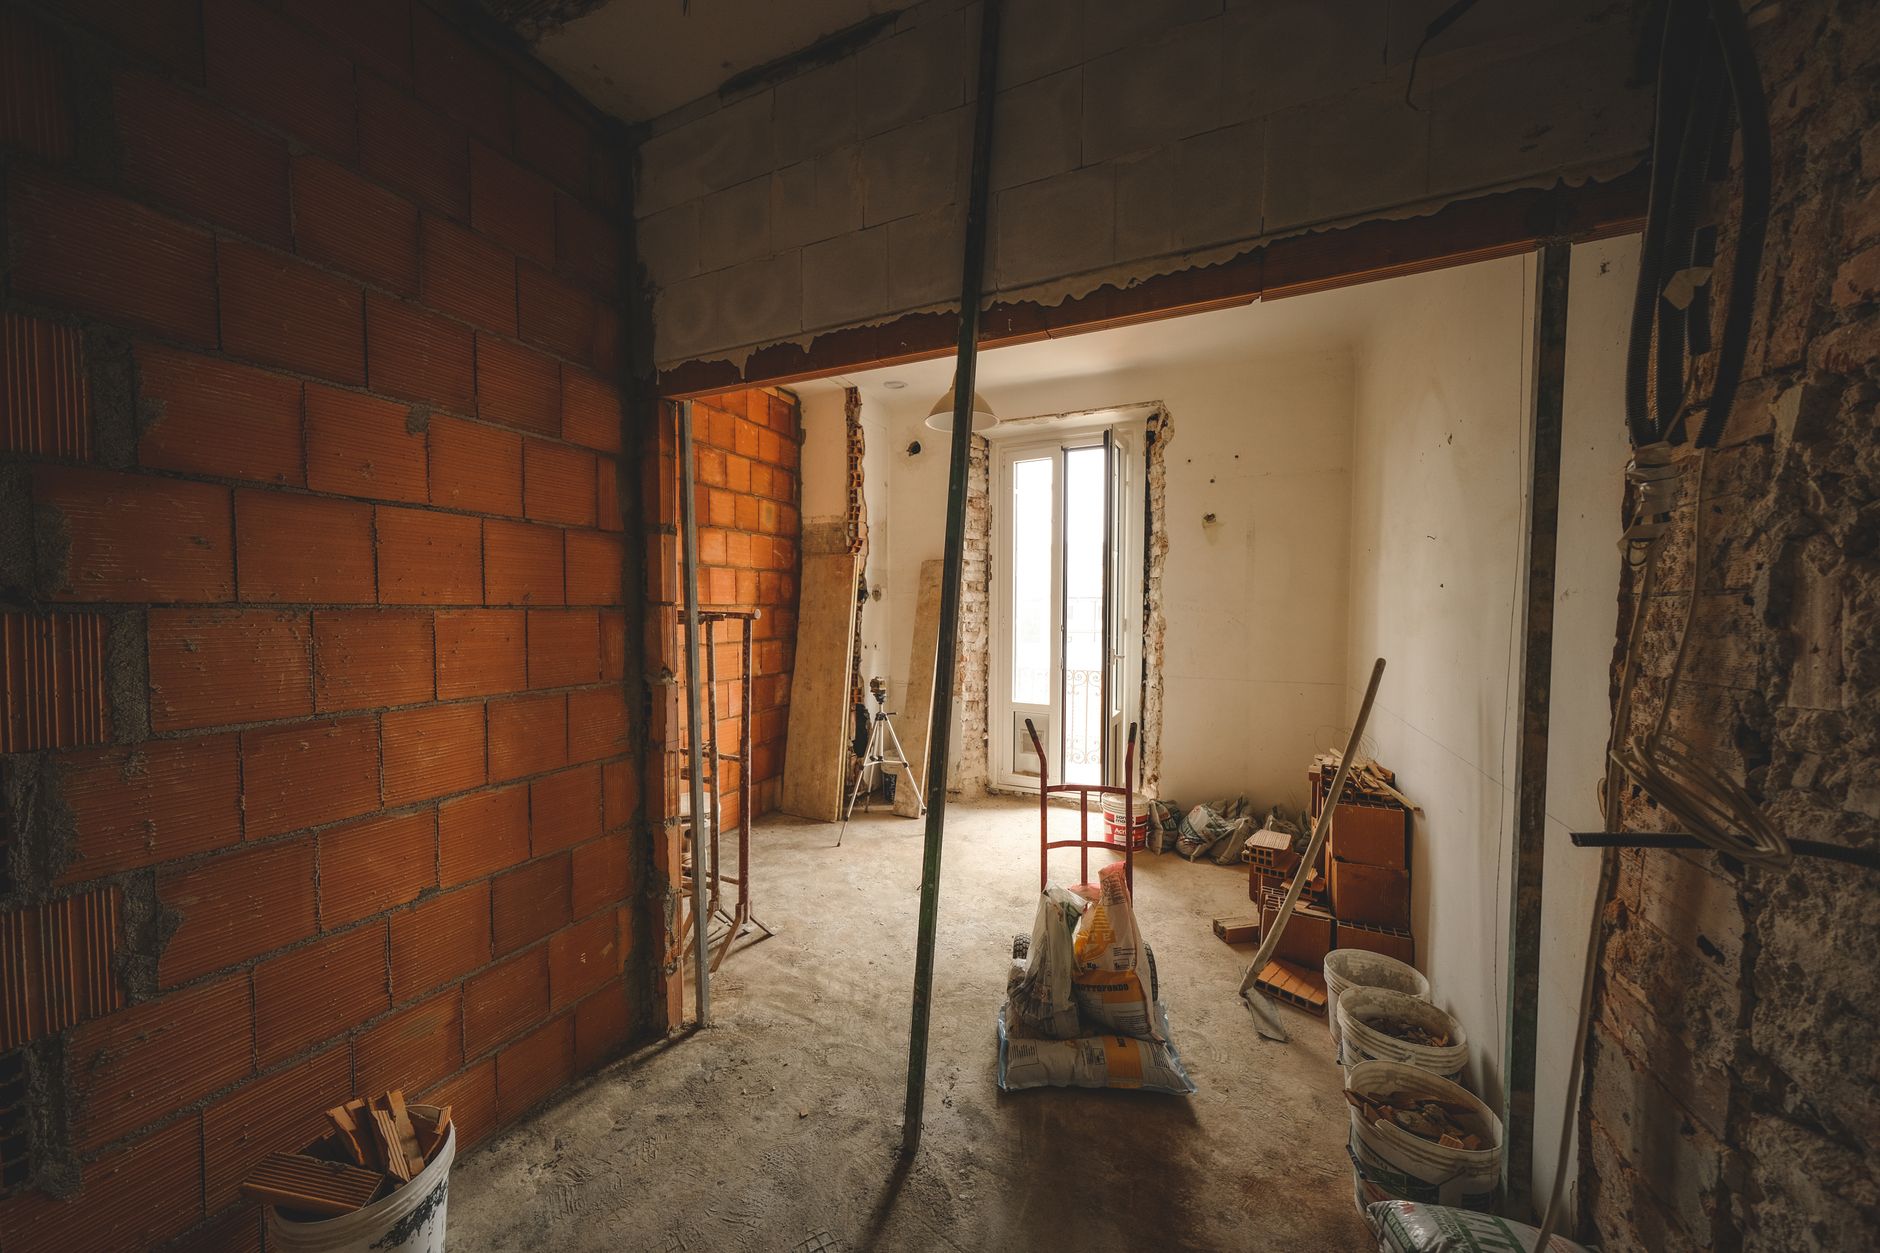
Structural and systems scope is roof, foundation and slab, exterior walls, windows and doors, electrical service and distribution, plumbing supply and drain lines, HVAC, seawall, and dock structure. This is where budgets move.
On older Gulf coast homes, watch for a few specific items. Cast iron drain lines were common in homes built through the 1970s and have a finite life; failure is disruptive because the lines run under the slab. Polybutylene supply piping, used in some construction from the late 1970s into the 1990s, is a known insurability concern and carriers frequently ask about it. Aluminum branch wiring from the mid-1960s to mid-1970s is another item insurers ask about. Original single-pane windows matter for both energy and, more importantly here, opening protection and wind resistance.
Have a general contractor walk the property with you during the inspection period — not just an inspector. An inspector tells you the condition. A contractor tells you the cost and the sequence.
Coastal Construction and Elevation Rules
This is the section that reclassifies projects, and it is the one most buyers have never heard of before they need it.
Under federal floodplain management standards adopted by local governments, a substantial improvement — generally defined as an improvement whose cost equals or exceeds fifty percent of the market value of the structure before the work — requires that the entire structure be brought into compliance with current flood-resistant construction requirements. The same rule applies to substantial damage. For a low-elevation older home in a flood zone, “brought into compliance” can mean elevating the structure.
That single rule is the difference between a renovation and a rebuild. A buyer planning a full gut renovation of an older cottage may find the project crosses the threshold and triggers requirements that change the entire economics.
Two things to know. First, the valuation used is the market value of the structure, not the property including land — and on a waterfront lot, land is usually the larger share, so the structure value can be lower than people assume. Second, some jurisdictions apply a cumulative substantial improvement standard, adding up improvements over a defined period rather than evaluating each permit in isolation.
Do not guess at any of this. Call the local floodplain administrator in the county or city with jurisdiction, give them the address and the scope you are contemplating, and ask directly how they would evaluate it. They answer this question routinely.
Separately, if the property sits seaward of Florida’s coastal construction control line, state-level review applies to construction there in addition to local permitting. That is a Gulf-front consideration primarily, and it is worth confirming early on any beachfront parcel.
Assembling Contractors Before You Close
The renovation timeline starts before the closing, not after it.
During the inspection period, bring in the trades whose numbers will actually determine feasibility: a general contractor for overall scope, a roofer if the roof is at or past its expected life, a marine contractor if the seawall or dock needs work, and an electrician if the panel or service looks original. Getting three of those four opinions before you remove your inspection contingency is worth far more than the inspection report alone.
At the same time, confirm insurability. A home that needs a roof and has original wiring may be difficult to insure at all in its current condition, and that can affect financing. Read our waterfront home insurance questions to ask before that conversation.
Verify contractor licensure through the Florida Department of Business and Professional Regulation and confirm current insurance. Marine work — seawalls, docks, lifts — is a distinct specialty from residential general contracting, and you generally want a marine contractor for it.
Sequencing a Renovation Realistically
The order matters more than most first-time renovators expect, and getting it wrong means doing work twice.
- Permits and design. Nothing physical starts until the permit set is approved. Build the review time into your calendar rather than treating it as a delay.
- Envelope first. Roof, windows, doors, and any exterior repair. There is no reason to install cabinetry under a roof you are about to replace.
- Marine structures. If the seawall needs work, do it before finishing the pool deck or landscaping behind it — heavy equipment needs access to the shoreline.
- Demolition and rough-in. Framing changes, electrical, plumbing, mechanical, and the inspections that close each of those out.
- Insulation, drywall, and interior finish. Flooring, cabinetry, tile, trim, paint.
- Pool and exterior. Resurfacing, cage work, decking.
- Landscaping last. Irrigation and plantings are the most easily damaged by everything preceding them.
Two habits separate projects that finish from projects that drag. Make selections early — fixtures, tile, cabinetry, appliances — because lead times, not labor, are the most common cause of stalls. And do not change scope mid-project; a change order after rough-in is dramatically more expensive than the same decision made at design.
Knowing When to Walk Away
Walk away when the permit record shows extensive unpermitted structural work with no clear path to resolution. Walk away when the seawall needs replacement and the marine contractor’s number turns the deal upside down. Walk away when the local floodplain administrator tells you your scope crosses the substantial improvement threshold and you are not prepared for what that entails. Walk away when you cannot get an insurance carrier to quote the property as it stands.
And walk away when your contractor is unwilling to give you a number. That is usually a signal about the property, not the contractor.
None of this makes coastal fixer-uppers a bad idea. It makes them a diligence-intensive idea, which is a different thing. The buyers who do well with them are the ones who pull the permit history in week one and call the floodplain administrator in week two.
If you are evaluating an older Gulf coast property and want help getting those calls made inside the inspection period, contact Sabatino Campilii.
Sabatino can answer it in five minutes — no pressure, no listing-agent spin.
Realtor®, License SL3363040
25-year builder, developer, and licensed Realtor® representing buyers and sellers across the Southwest Florida Gulf-coast pockets. Reviewed and published July 2, 2026.
Have Sabatino represent you — before you call any listing agent.